Wealth building
Build long-term wealth with strategies for investing, saving and managing your cash flow.
We help you make confident financial decisions today, so you can enjoy a more secure tomorrow.
Build long-term wealth with strategies for investing, saving and managing your cash flow.
Protect what matters most with insurance, estate planning and strategies for life's moments.
Plan for a comfortable retirement with personalised strategies for every stage of later life.
Our investment solutions are designed to help you build, protect and grow your wealth.
Discover our investment philosophy, meet our team and explore the strategies that help clients invest with confidence.
Expert accounting services and tailored advice to support your financial success and help your business thrive.
Tax returns, planning and advice tailored to your individual financial situation.
Accurate, reliable bookkeeping to keep your records organised and up to date.
Comprehensive SMSF administration with expert guidance.
Expert lending advice to help you finance your next home, investment or business opportunity with confidence.
Our Lending Team
Meet the team making your funding desires a reality.
Finance your next home or investment property with tailored lending solutions.
Review your current loan and explore opportunities to reduce repayments or unlock equity.
Funding solutions to help your business grow or expand with finance tailored to your needs.
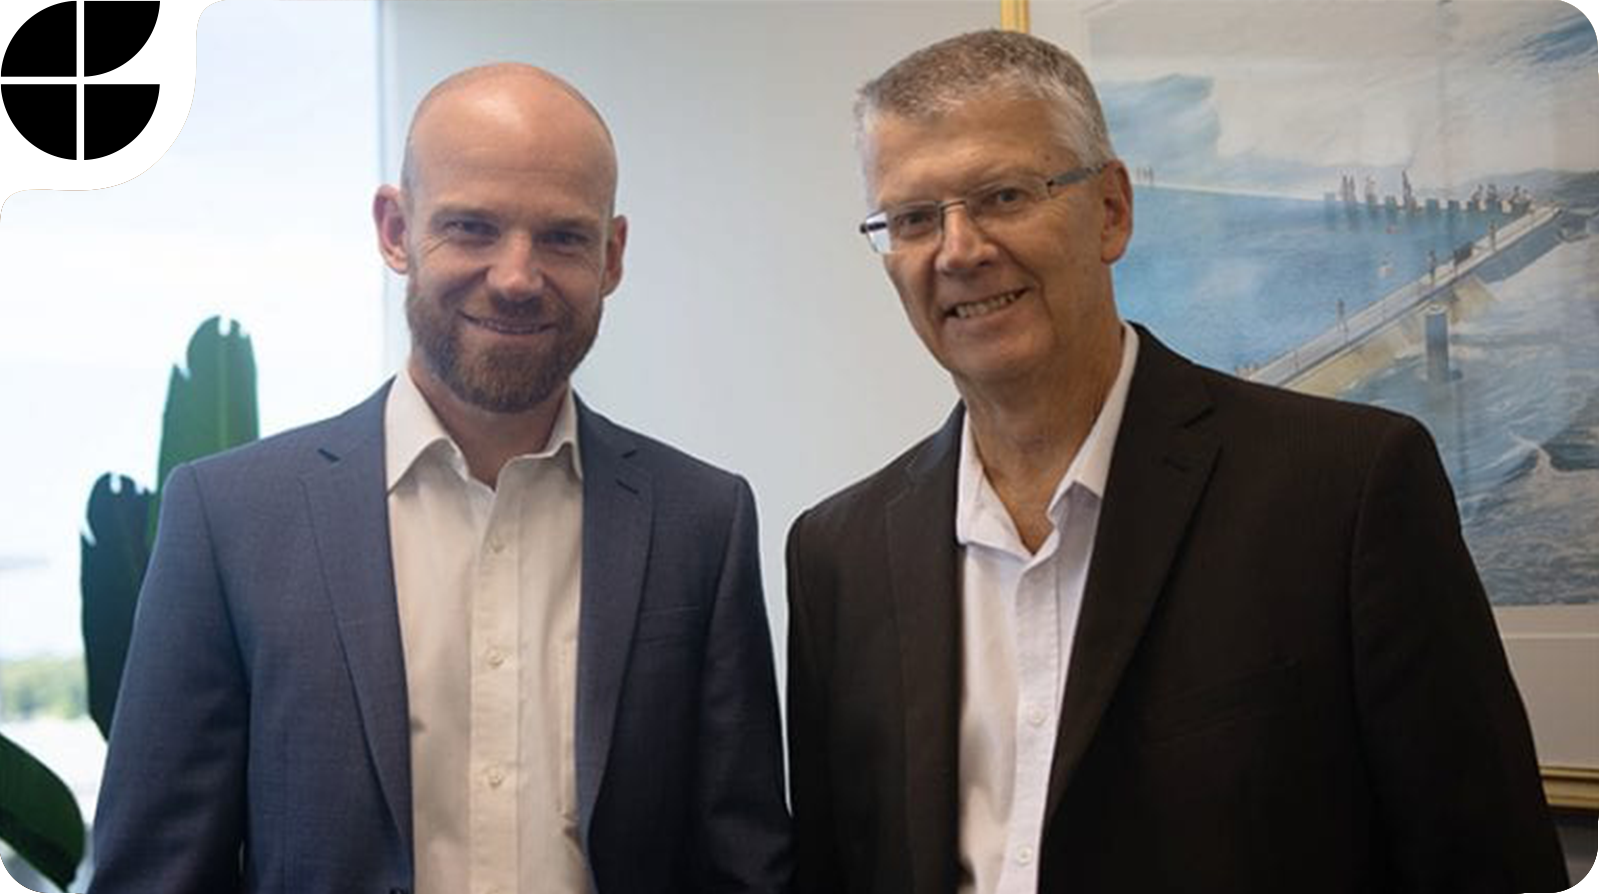
Get to know the people, values and story behind Count Wealth.
Discover how we began and where we're going.
Extensive expertise with practical, real-world business knowledge
Contact us today